


Greater Madrid has strengthened its position as Spain’s leading commercial real estate investment destination in 2026, attracting €6.471 billion in the first three quarters of the year, compared with €3.679 billion over the same period in 2025, according to Iberian Property preliminary estimates. The increase of approximately 76% significantly outpaced the growth of the Spanish market as a whole, where investment rose from €10.226 billion to €13.998 billion, an increase of around 37%.
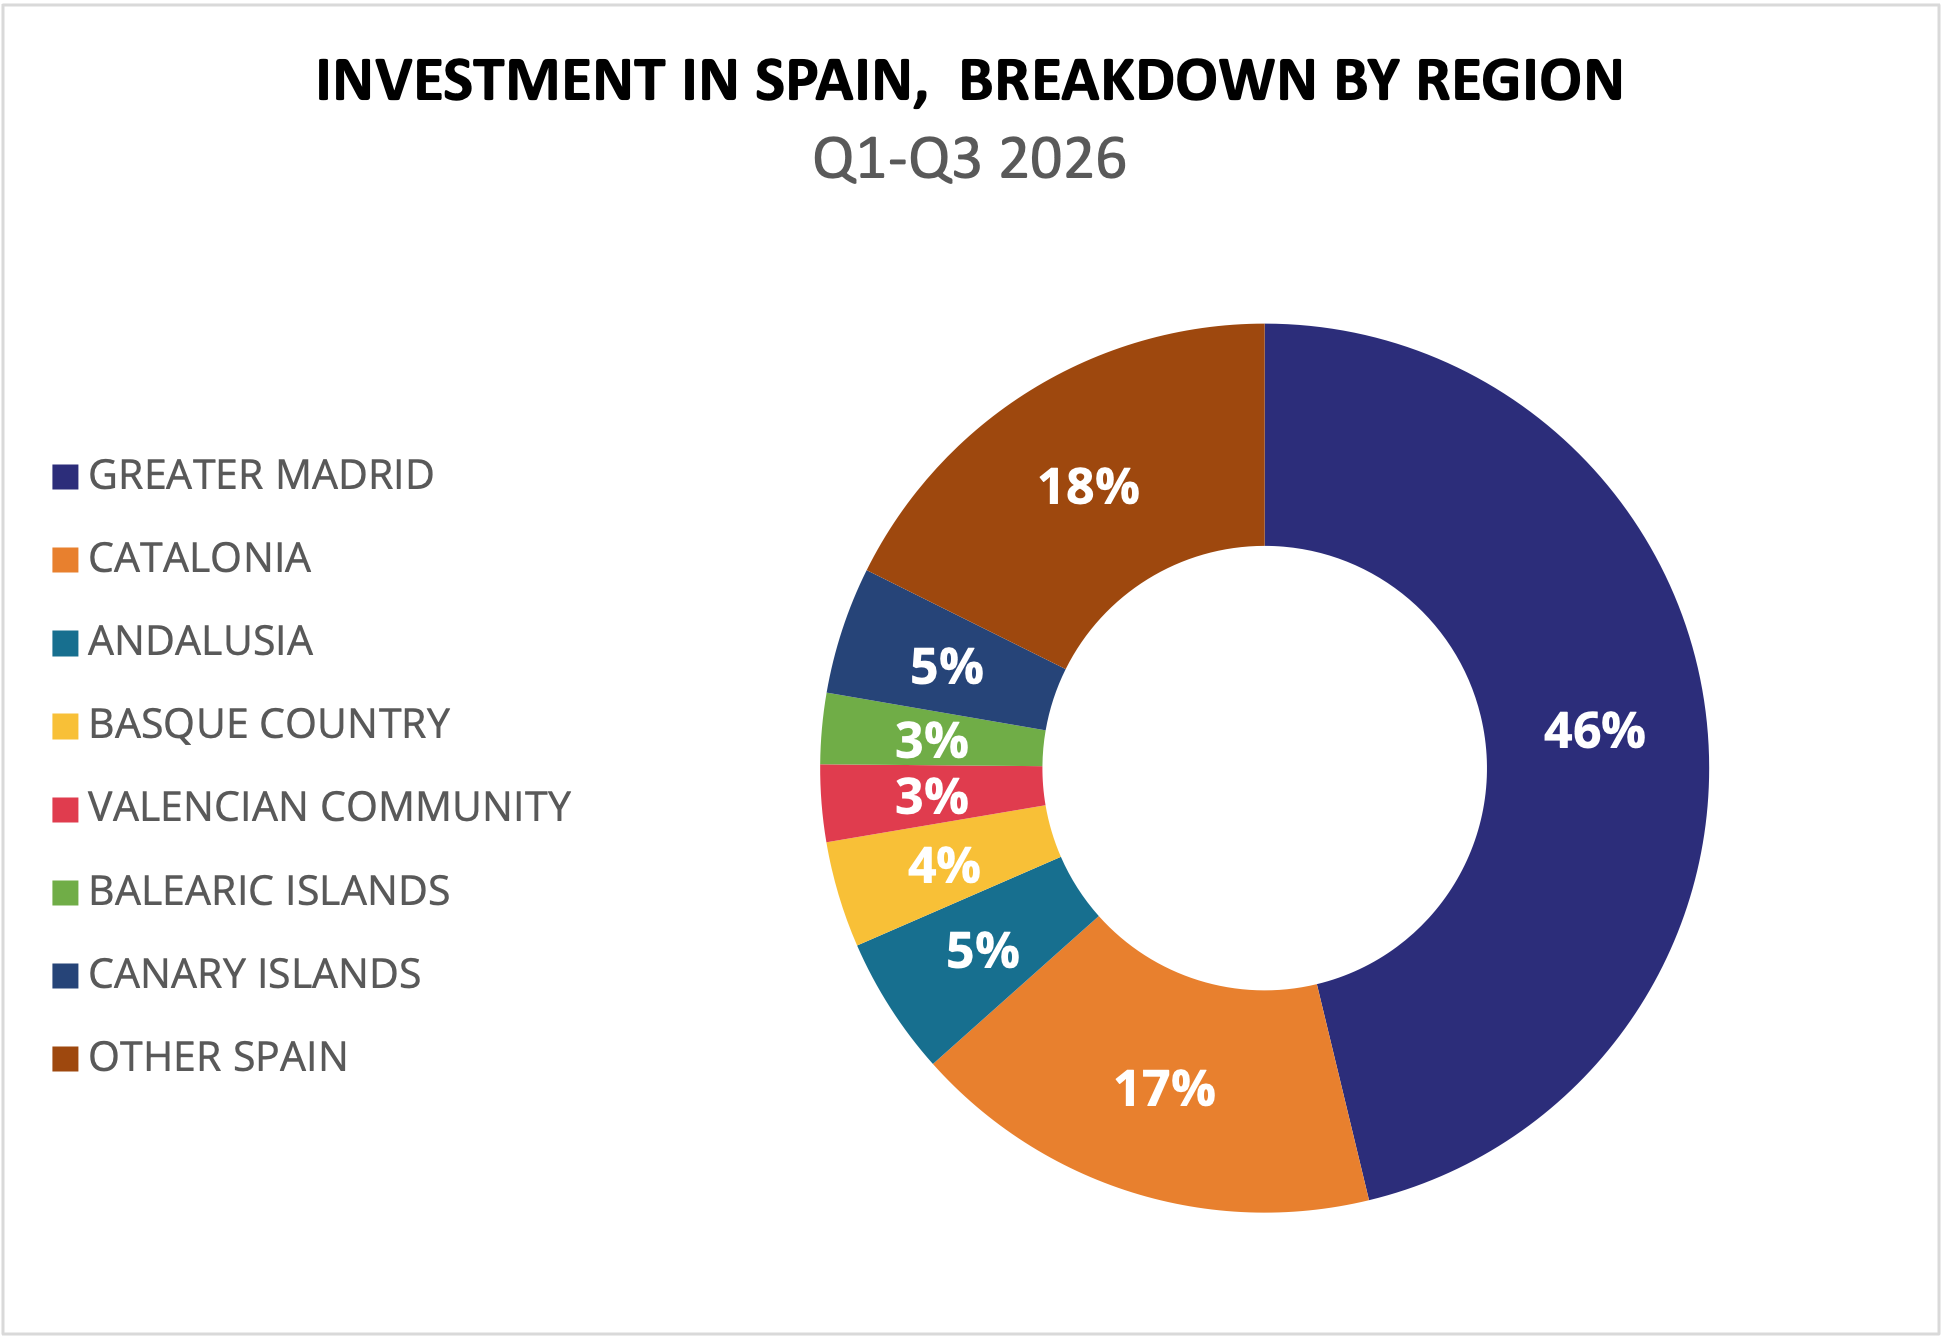
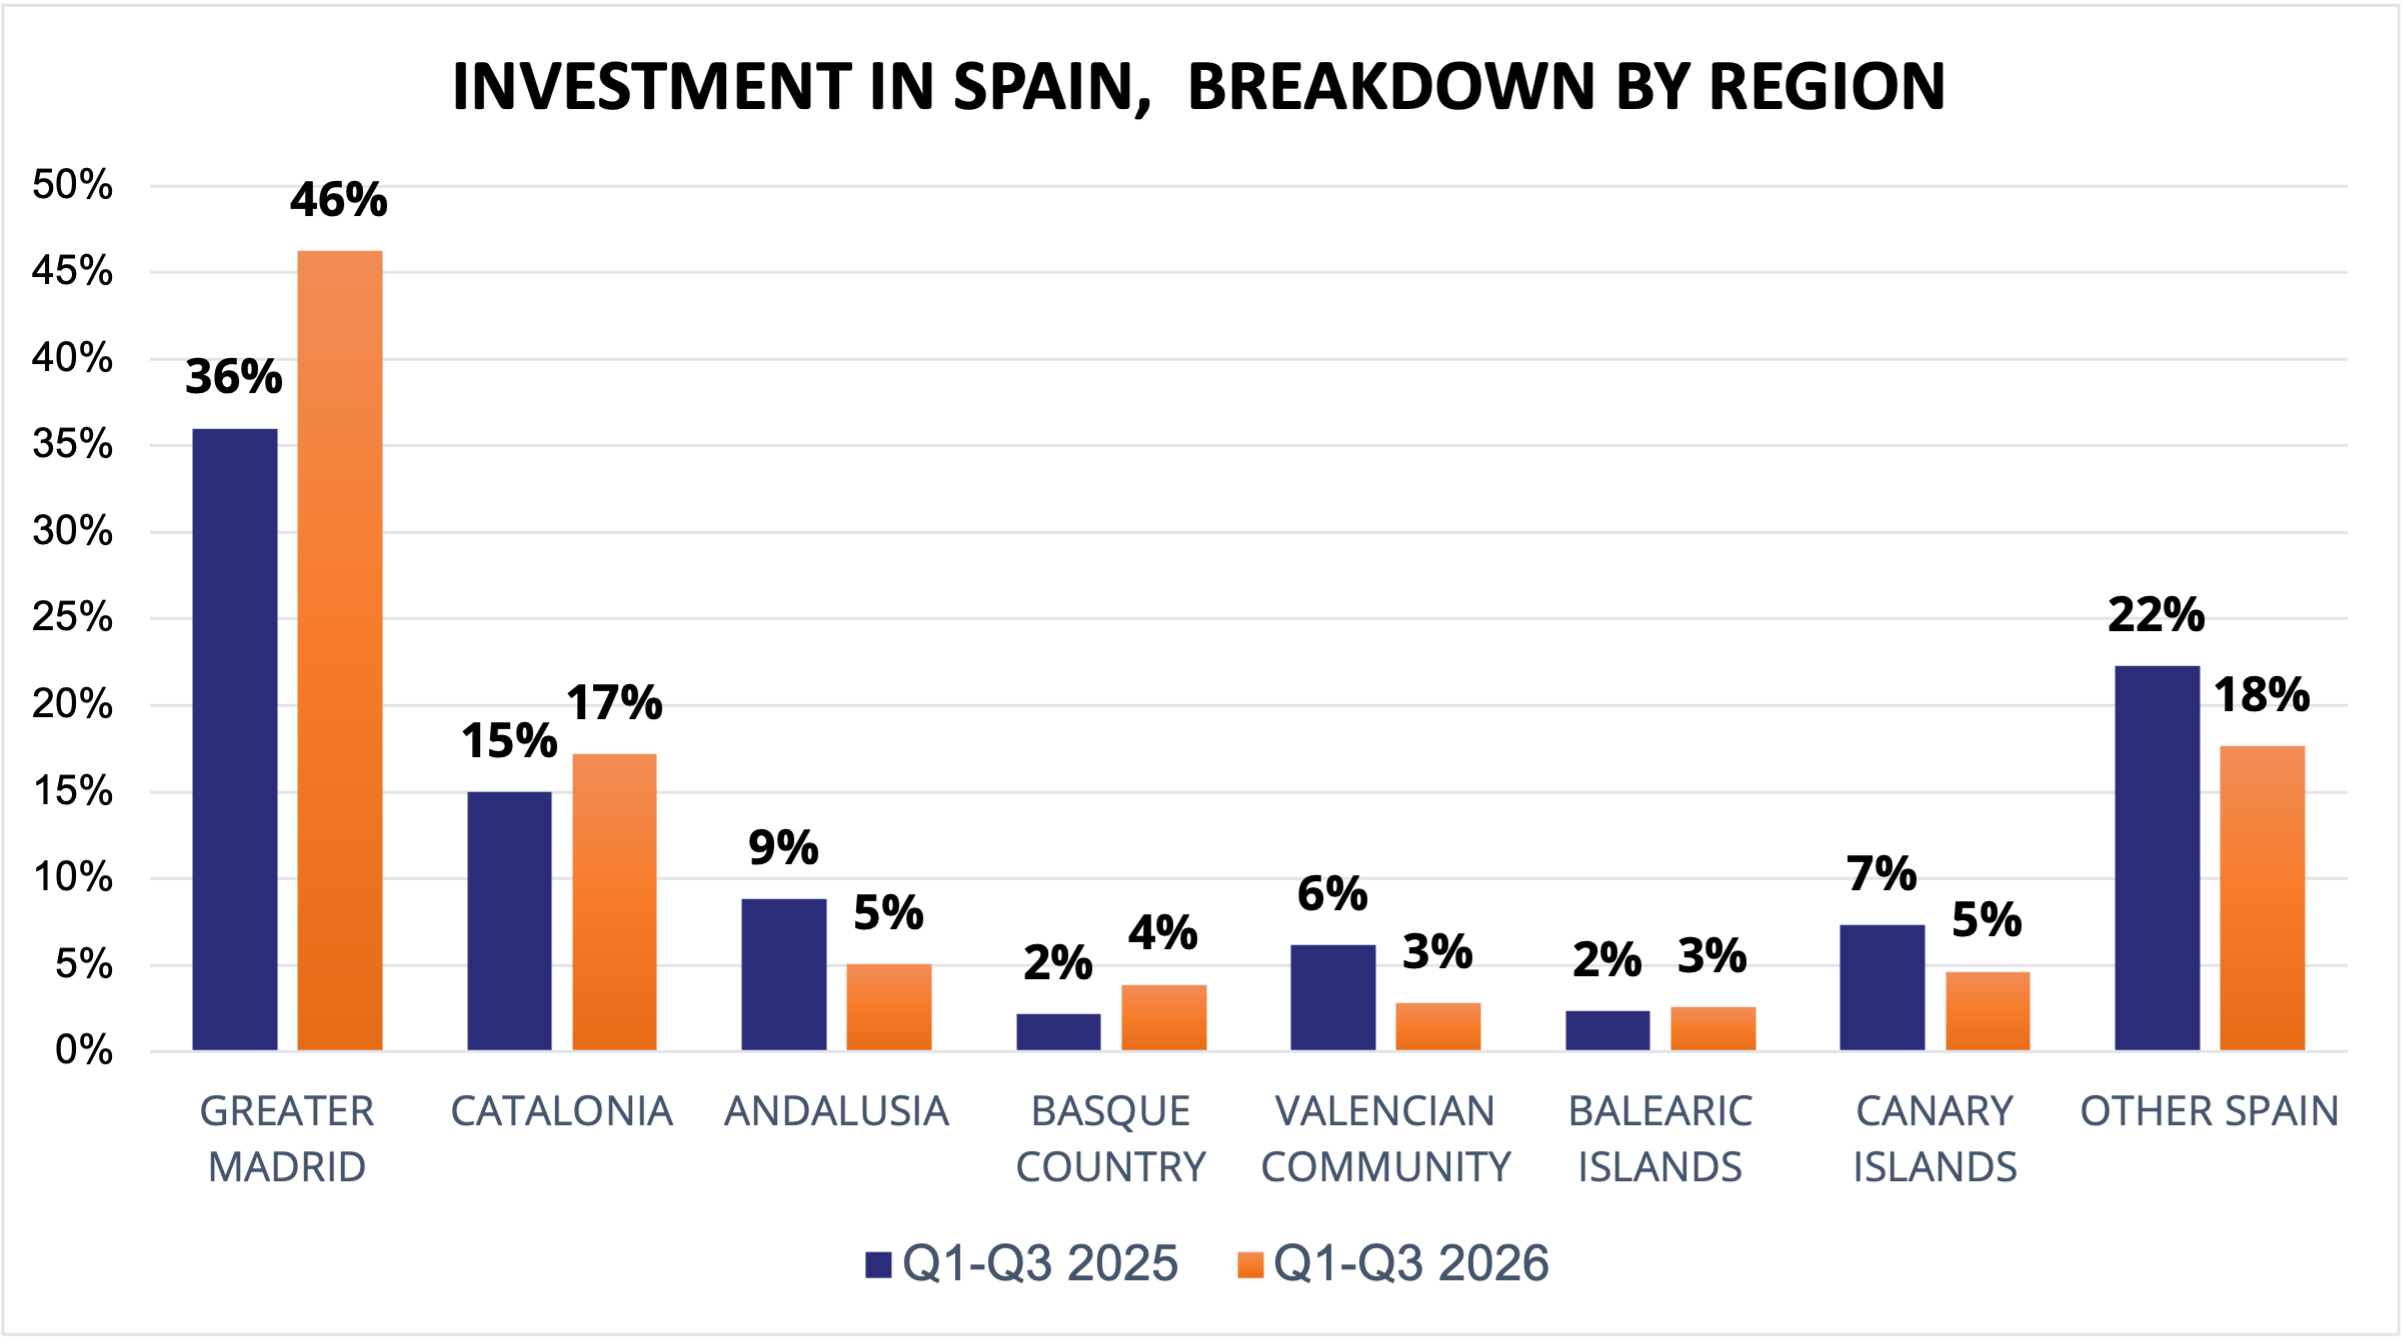
Madrid’s share of national investment consequently climbed from 36% in Q1–Q3 2025 to 46% in the same period this year, gaining 10 percentage points in just 12 months. The region’s investment volume has already exceeded its full-year 2025 total of €4.815 billion by approximately 34%, underlining the scale of the acceleration.
The pace of activity also strengthened as the year progressed. Madrid recorded €1.851 billion in investment in the first quarter, followed by €2.118 billion in Q2 and €2.501 billion in Q3. The latest quarter was therefore the strongest of the year so far, suggesting that the market’s momentum continued beyond the large transactions completed in the first half.
Residential and retail lead investment activity
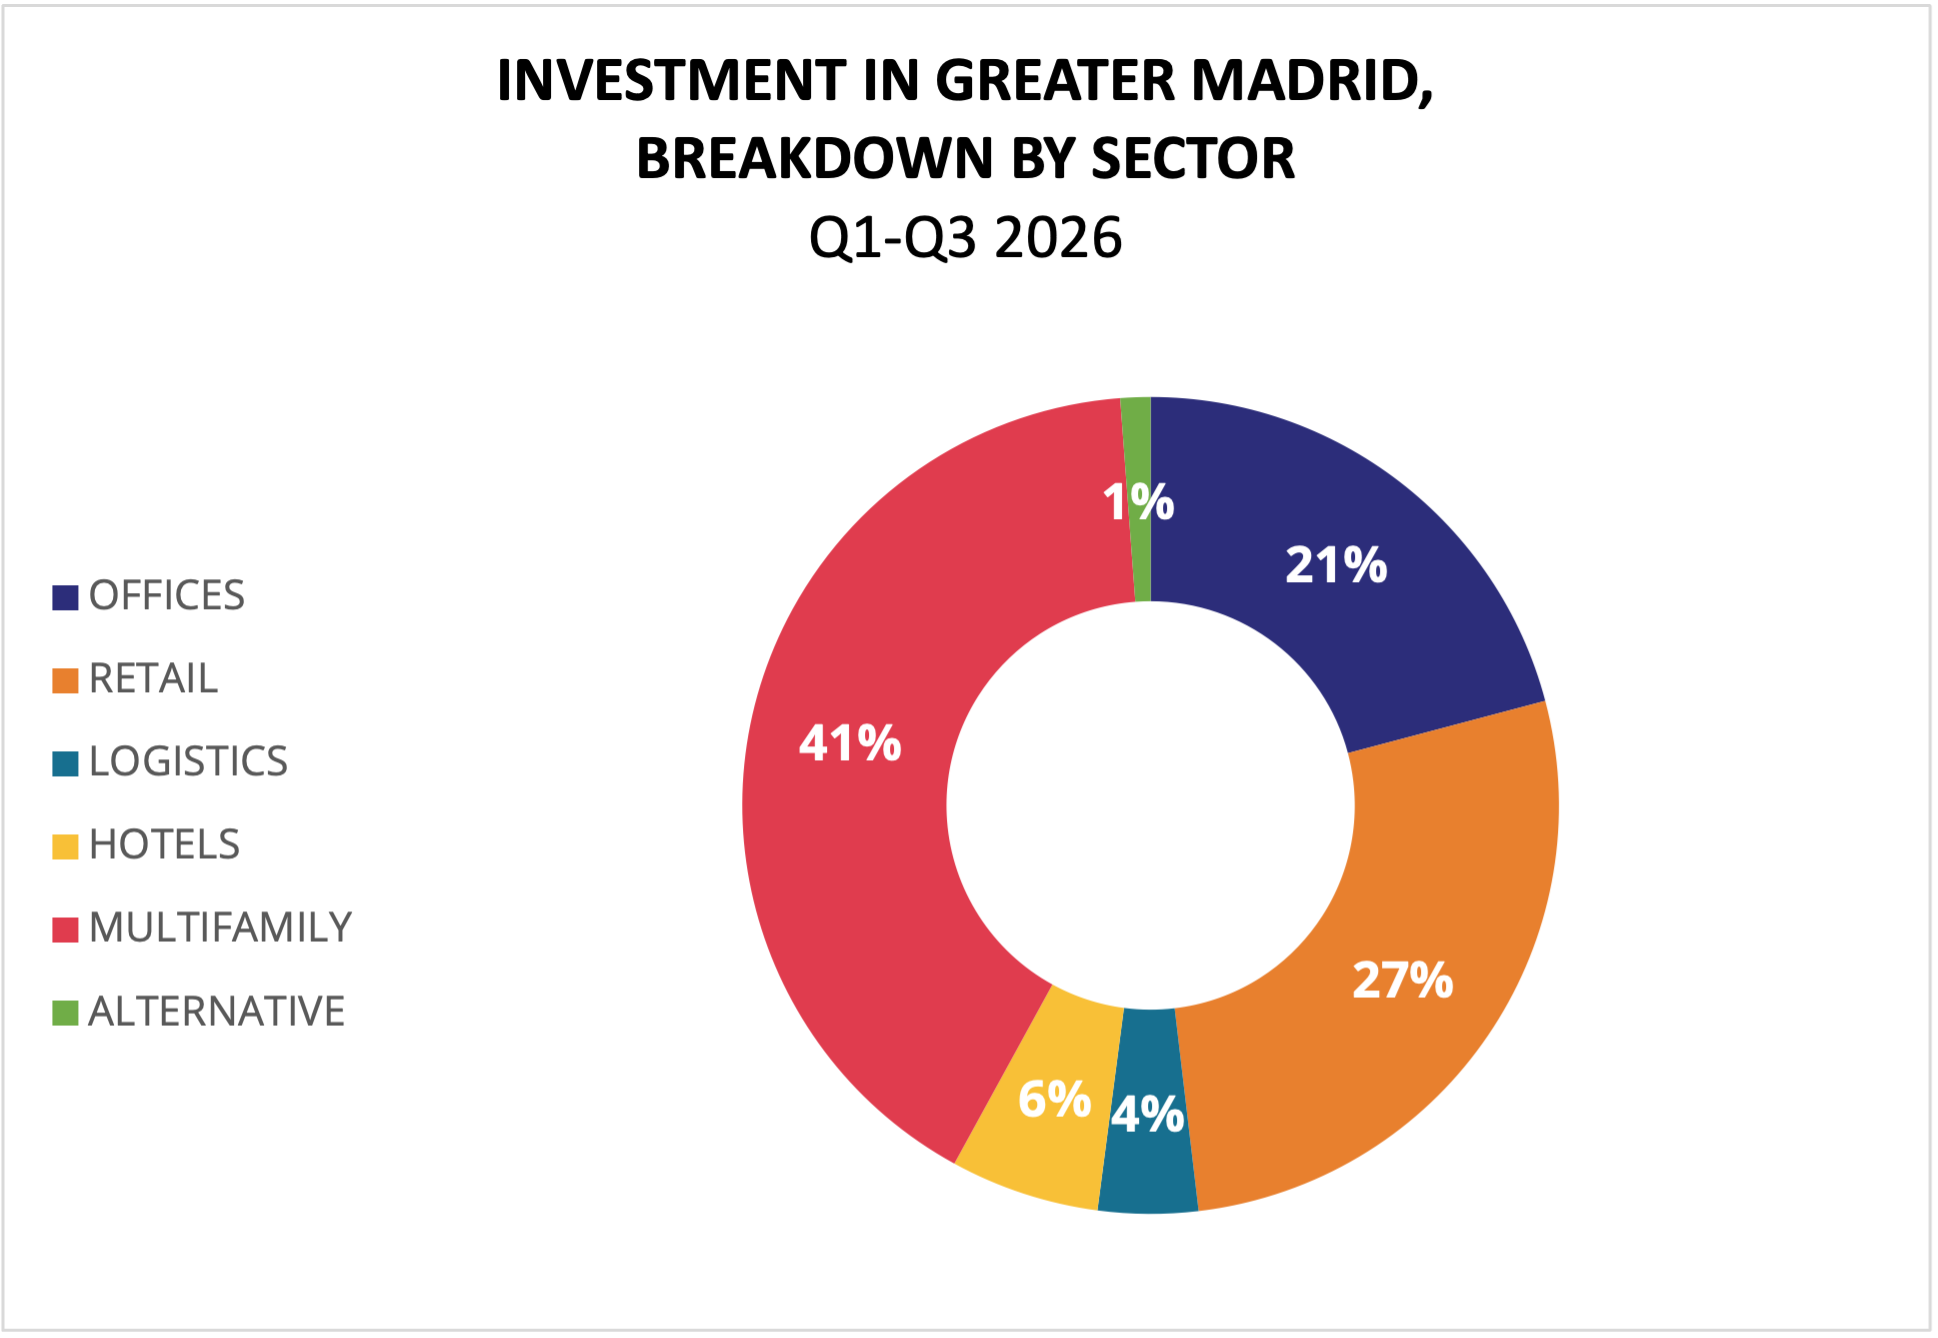
Multifamily was Madrid’s largest investment sector in the first nine months of 2026, accounting for 41% of the regional total, equivalent to €2.642 billion. Retail followed with €1.763 billion, or 27%, while offices attracted €1.351 billion, representing 21% of investment. Hotels accounted for €382 million, logistics for €256 million and alternative assets for €77 million.
Together, multifamily and retail represented approximately €4.4 billion, or 68% of Madrid’s investment volume. The figures highlight the importance of residential platforms and established retail destinations to the region’s current investment profile, while office transactions also made a substantial contribution. Hotels and logistics accounted for smaller shares of the total, although individual transactions across both sectors continued to feature in the market.
The largest transaction recorded in Madrid during the period was Brookfield’s acquisition of Fidere from Blackstone, valued at €1.05 billion in Iberian Property’s data. The residential transaction was followed by the sale of six shopping centres from a wider Spanish portfolio to Norges Bank Investment Management and Sonae Sierra, with an estimated €1 billion allocated to the six Madrid assets in Iberian Property’s figures. The portfolio transaction was one of the defining retail deals of the year, illustrating the capacity of large, established assets to attract substantial institutional capital.
Residential investment was further supported by the acquisition by the Healthcare of Ontario Pension Plan (HOOPP) of a portfolio of approximately 2,300 homes from Ares Management, valued at €690 million. Together, the Fidere and HOOPP transactions demonstrate the importance of large residential portfolios in shaping Madrid’s investment totals, alongside continued demand for income-producing retail assets.
Major transactions shape the market
The five largest deals in Iberian Property’s Q1–Q3 2026 data totalled approximately €3.33 billion, representing around 51% of the region’s recorded investment. In addition to Fidere, the six shopping centres and the HOOPP residential portfolio, the list includes Castellana Properties’ €340 million acquisition of Islazul shopping centre from Henderson Park and Eurofund, and Rivoli Asset Management’s €250 million purchase of a 50% stake in Xanadú shopping centre from Nuveen Real Estate.
The concentration of investment in these large transactions is an important feature of the period. While the headline deals account for more than half of the regional total, the wider transaction pipeline shows activity across a broader range of asset types and lot sizes, from individual office buildings and hotels to residential buildings, student accommodation, logistics facilities and build-to-rent portfolios.
Office transactions included Square AM’s acquisition of Omega Business Park for €104 million, Grupo Insur’s purchase of La Sierra Business Area for €81 million and IBA Capital Partners’ €85 million acquisition of the MBOne office building from Grosvenor. Other activity included the €105 million sale of the Nômade Madrid hotel by Hotei Properties to GS Bacares Iberia, as well as Meridia Capital’s €130 million acquisition of a 977-unit flex-living asset in Carabanchel from a Bain Capital, Momentum REIM and Episode vehicle.
The build-to-rent segment also recorded two significant transactions in September, when Starwood Capital acquired the Stay by Kronos Berrocales and Alcalá de Henares portfolios from Nuveen Real Estate for €130 million and €50 million respectively, covering a combined 1,154 homes. Student housing featured in the period as well, with Westwind Capital acquiring an 837-bed residence next to the Polytechnic University of Madrid from Merkel Capital for €90 million.
These transactions point to a market in which large portfolio deals coexist with continued activity in individual assets and specialist living formats. They also show that Madrid’s investment story extends beyond its largest residential and retail transactions, with capital moving through offices, hospitality, logistics, student accommodation, flex living and rental housing.
Madrid consolidates its lead over the rest of Spain
Madrid’s growing share of national investment is particularly notable against the performance of other major Spanish markets. Catalonia attracted €2.405 billion in Q1–Q3 2026, up from €1.533 billion a year earlier, and increased its share of national investment from 15% to 17%. By comparison, Andalusia recorded €708 million, down from €901 million, while the Valencian Community attracted €393 million, compared with €628 million in the same period of 2025. The Basque Country increased its volume from €222 million to €541 million, while the Balearic Islands rose from €238 million to €361 million.
Madrid’s €6.471 billion total was therefore substantially ahead of Catalonia, the country’s second-largest regional market, and represented more than two and a half times its investment volume. Its performance also stands out for the speed at which its lead has widened: the region’s share of national investment increased while the Spanish market itself expanded, demonstrating that Madrid’s growth was not simply a reflection of a stronger national investment environment.
With €6.47 billion already recorded by the end of September, Greater Madrid enters the final quarter of 2026 from a position of strength. The combination of large-scale residential portfolios, landmark retail transactions and activity across a wider range of commercial property sectors has made the region the principal driver of Spain’s real estate investment market so far this year.

